“I have to enter the amounts by hand, and I forget if I don't do it right after I pay.”
- Income
- 50 to 60 million VND a month
- Needs
- One place to track business and personal spending
- Struggles
- Often spends past her budget and pays card interest
A buy-now-pay-later wallet for Vietnam, taken from problem statement and personas to a finished mobile app.
Client
LIT (freelance)
Role
Product designer, UX research and UI
Year
2023
Platform
Mobile app
Market
Vietnam
Scope
Research in 13 steps, sitemap, style guide, eight app flows
Built on
Asgard Design Kit, my own design system
Status
Product design handed over to LIT

Context
By 2023, buy now, pay later had become a common way to pay for clothing and electronics. Food and drinks, cosmetics, education and entertainment were mostly left out. People who wanted to try it ran into three problems: they were not sure how it worked, every service wanted its own account, and approval took too long.
LIT brought me in to research the problem and design the app. I built it around those three problems: one account for every partner store, a credit limit after a single identity check, and installments online or at the counter.
Research
The problem and the business strategy set the scope. LIT’s team ran the survey and interviews; I turned their findings into three personas, a journey map and an empathy map. A competitor review and a SWOT placed LIT in the market. Two prioritisation matrices and a set of success metrics turned it all into a first release.
Strategy
What people need
What LIT has to do
Buy what they need without paying in full today
Offer a flexible way to pay that does not drain savings
Pay back in smaller installments
Keep installments affordable, without sliding into debt
Use one account across many stores
Work as one checkout at any partner store
Sign up and start quickly
Keep sign-up short, so LIT is usable the same day
Trust that their data is safe
Protect payments and personal data
Who it is for
The target group is 25 to 35, living in large cities, on average or higher incomes. They shop online often, follow trends and have little set aside. They named three fears: being scammed online, paying too much, and falling into debt.
“I have to enter the amounts by hand, and I forget if I don't do it right after I pay.”
“I can just use my fingerprint to authorize all transactions.”
“When I use a credit card, it's hard to see where my money has gone.”
What we heard
LIT’s team surveyed and interviewed ten people in the target group about how they use BNPL, what they like and what holds them back. They valued paying later and splitting a purchase into installments, which made spending easier to plan. Their concerns were late fees and buying more than they could afford. Most had used BNPL only for clothing, shoes and electronics.
“I like BNPL because it's flexible. I can split my payments into multiple installments, which helps me manage my finances better.”
“I am concerned about the fees associated with BNPL, such as late fees.”
“I am concerned that BNPL can lead to overspending.”
“I don't want to pay a high interest rate.”
“I need a payment solution with a quick and easy approval process.”
“I have used other payment solutions in the past, but the approval process was often slow.”
Survey and interviews by LIT’s team, ten participants, 2023. A small sample, used to shape the personas and the journey, not to size the market.
Journey map
The journey runs from first hearing about LIT to recommending it. Confidence rises through research and sign-up, then drops at first use, when people have questions about how the features work. That dip pointed to what the app needed right after sign-up: guidance for new users and support that is easy to reach.
Market
I compared five services people in Vietnam already used in 2023. Fundiin was interest-free, with 171 partners and a three-month term. Paylater and FE Credit spread payments over up to 12 and 36 months, but charged 31 to 37% a year and took 20 to 40 minutes to approve. MoMo came closest, with 0% interest and 12,000+ partners, but its postpaid wallet is paid back in one go after 30 days. LIT’s opening was installments at 0%, at any partner store, after one check.
| Fundiin | Paylater | MoMo | FE Credit | |
|---|---|---|---|---|
| Model | Buy now, pay later | BNPL and installment loans | Postpaid e-wallet | Cash loans, installments, cards |
| Where you pay | Online and in store | Partner websites | Online and in store | Online and in store |
| Partners | 171 | 20+ | 12,000+ | 9,000+ |
| Interest | 0% a year | 31% a year | 0% | 37% a year |
| Term | 3 months | 3 to 12 months | 30 days | 6 to 36 months |
| Approval | 5 to 10 minutes | 20 to 30 minutes | Under 5 minutes | 20 to 40 minutes |
Public information collected in 2023. Terms may have changed since. Halo was reviewed but published no terms.
One wallet across retailers. A short sign-up.
A new, unknown name. May not suit people with low credit scores.
A fast-growing BNPL market. More retail partners.
Established BNPL players. New regulation. Fraud and cyber attacks.
Priority
An Eisenhower matrix and an impact-effort matrix split the ideas into two groups. The first release covers one place to shop and pay, buying now and paying later at 0% interest, and tools to keep track of spending. More payment methods, rewards and loyalty programs wait for later.
Decision
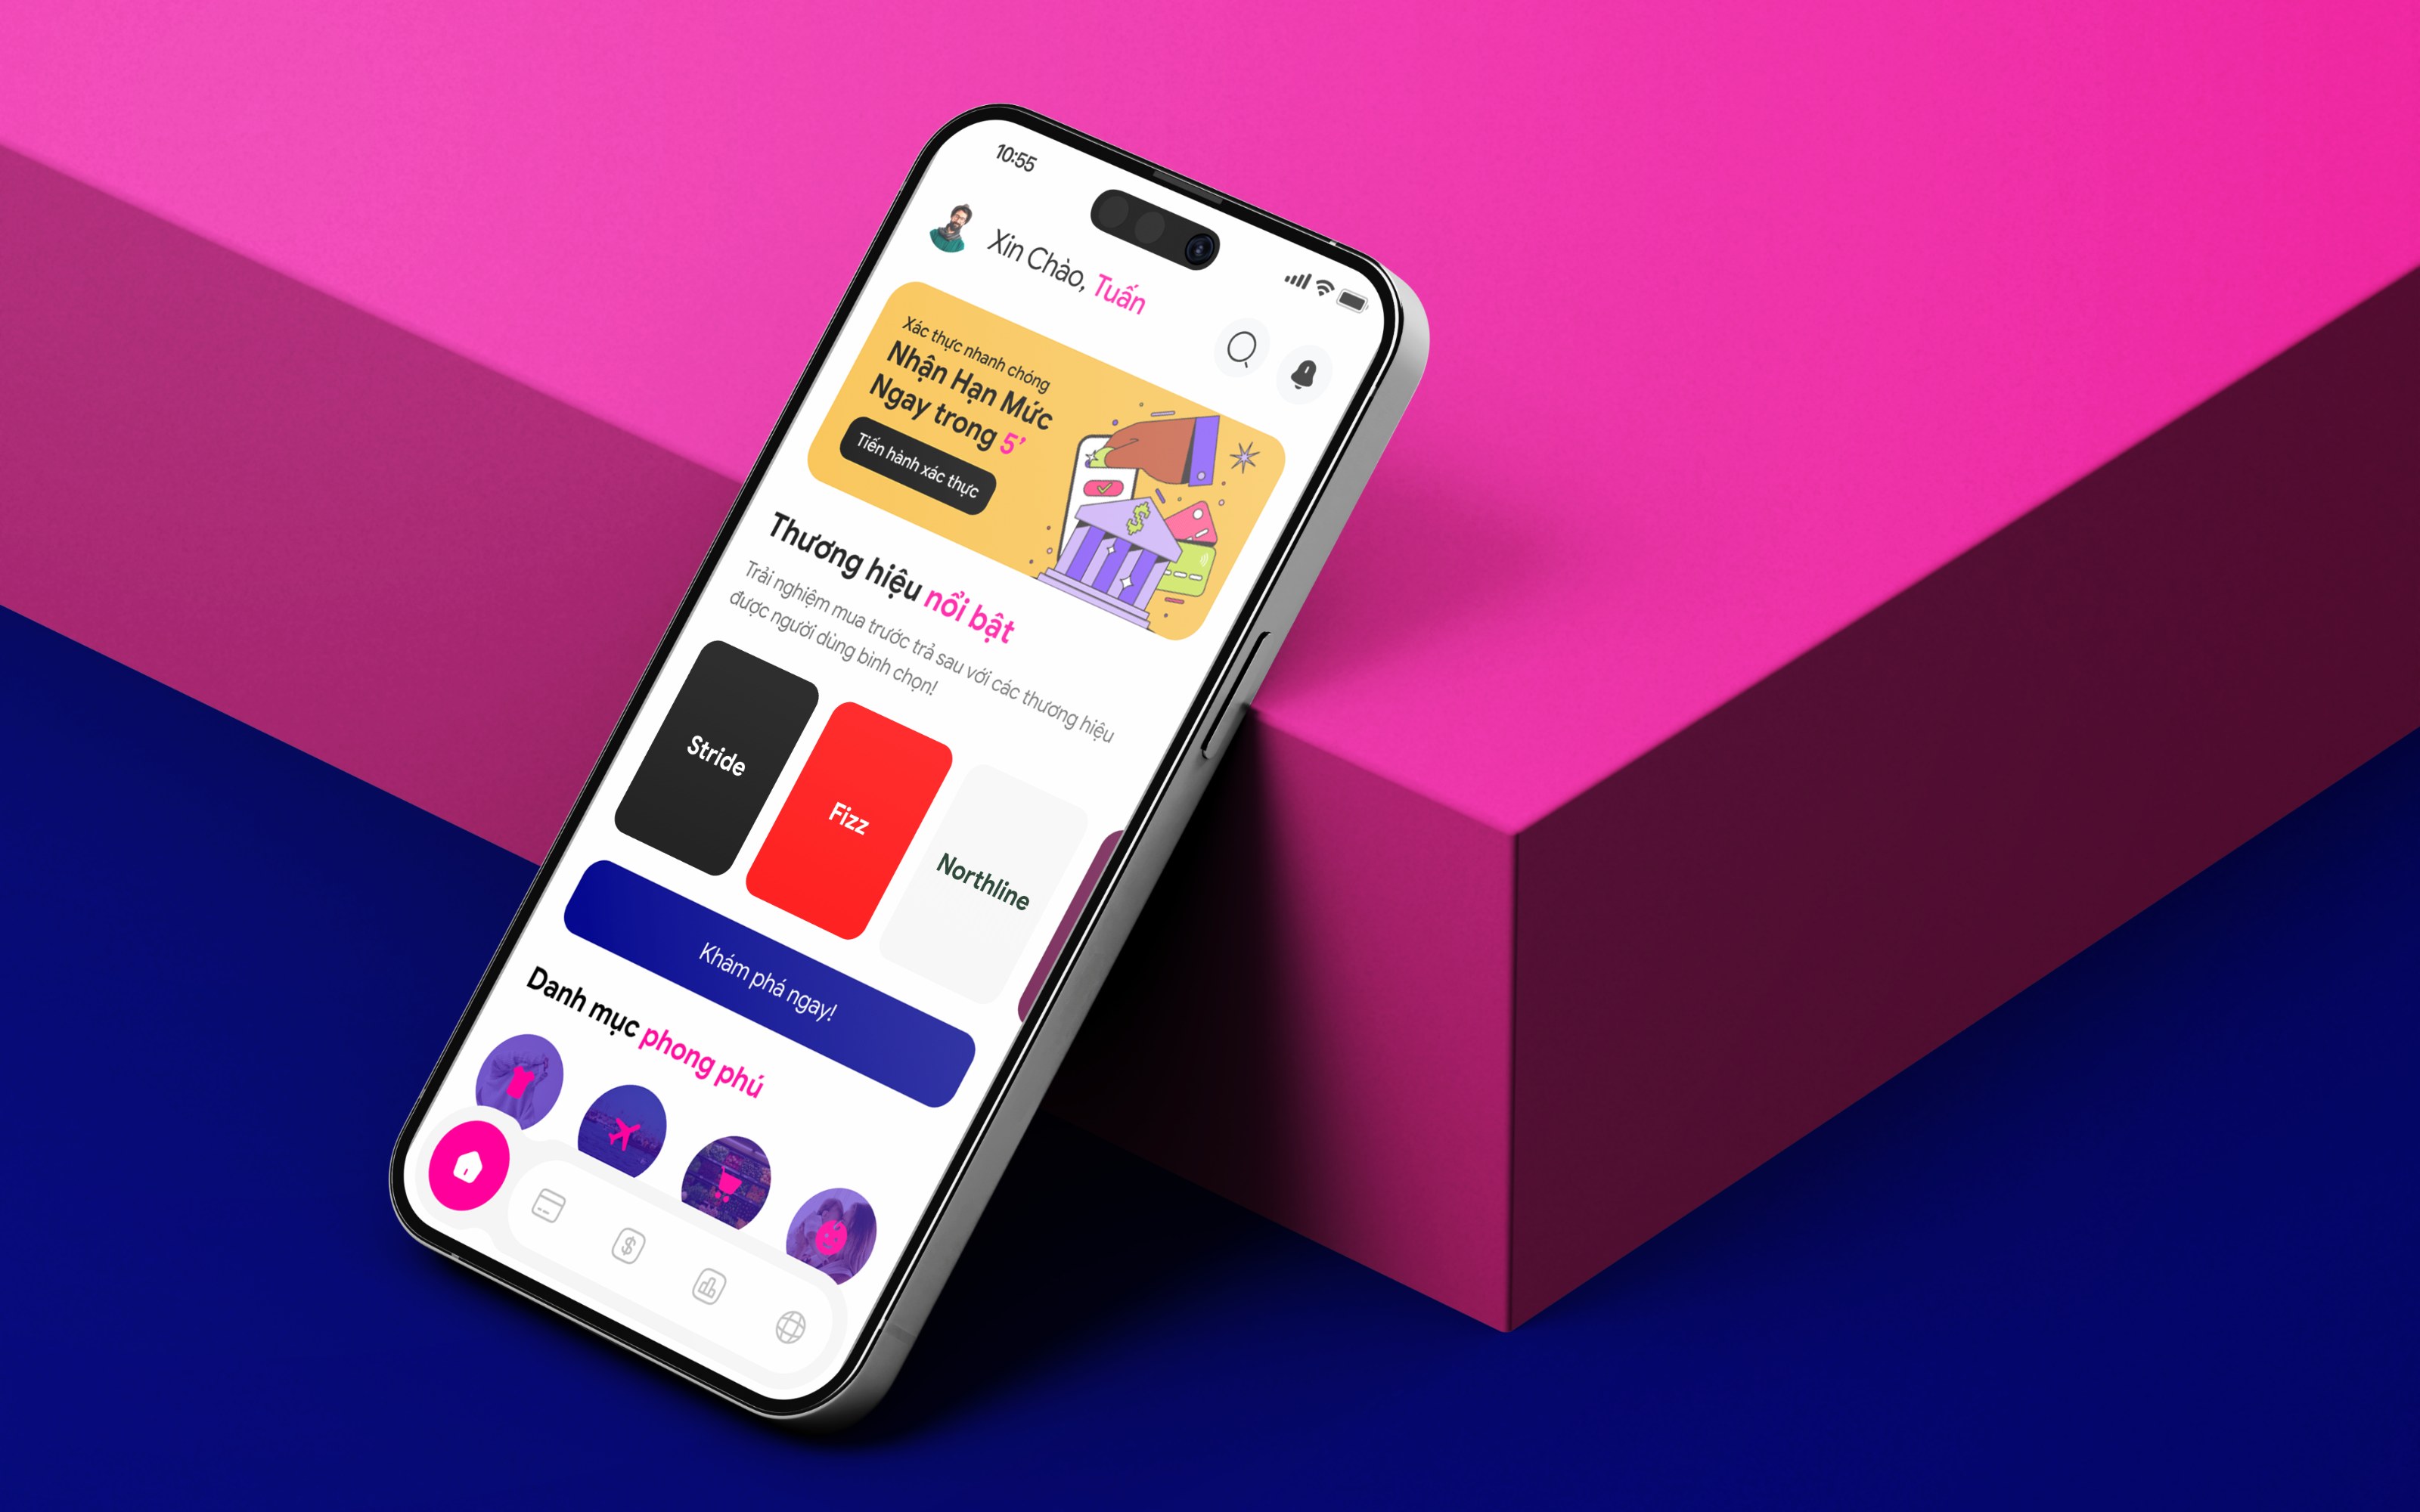
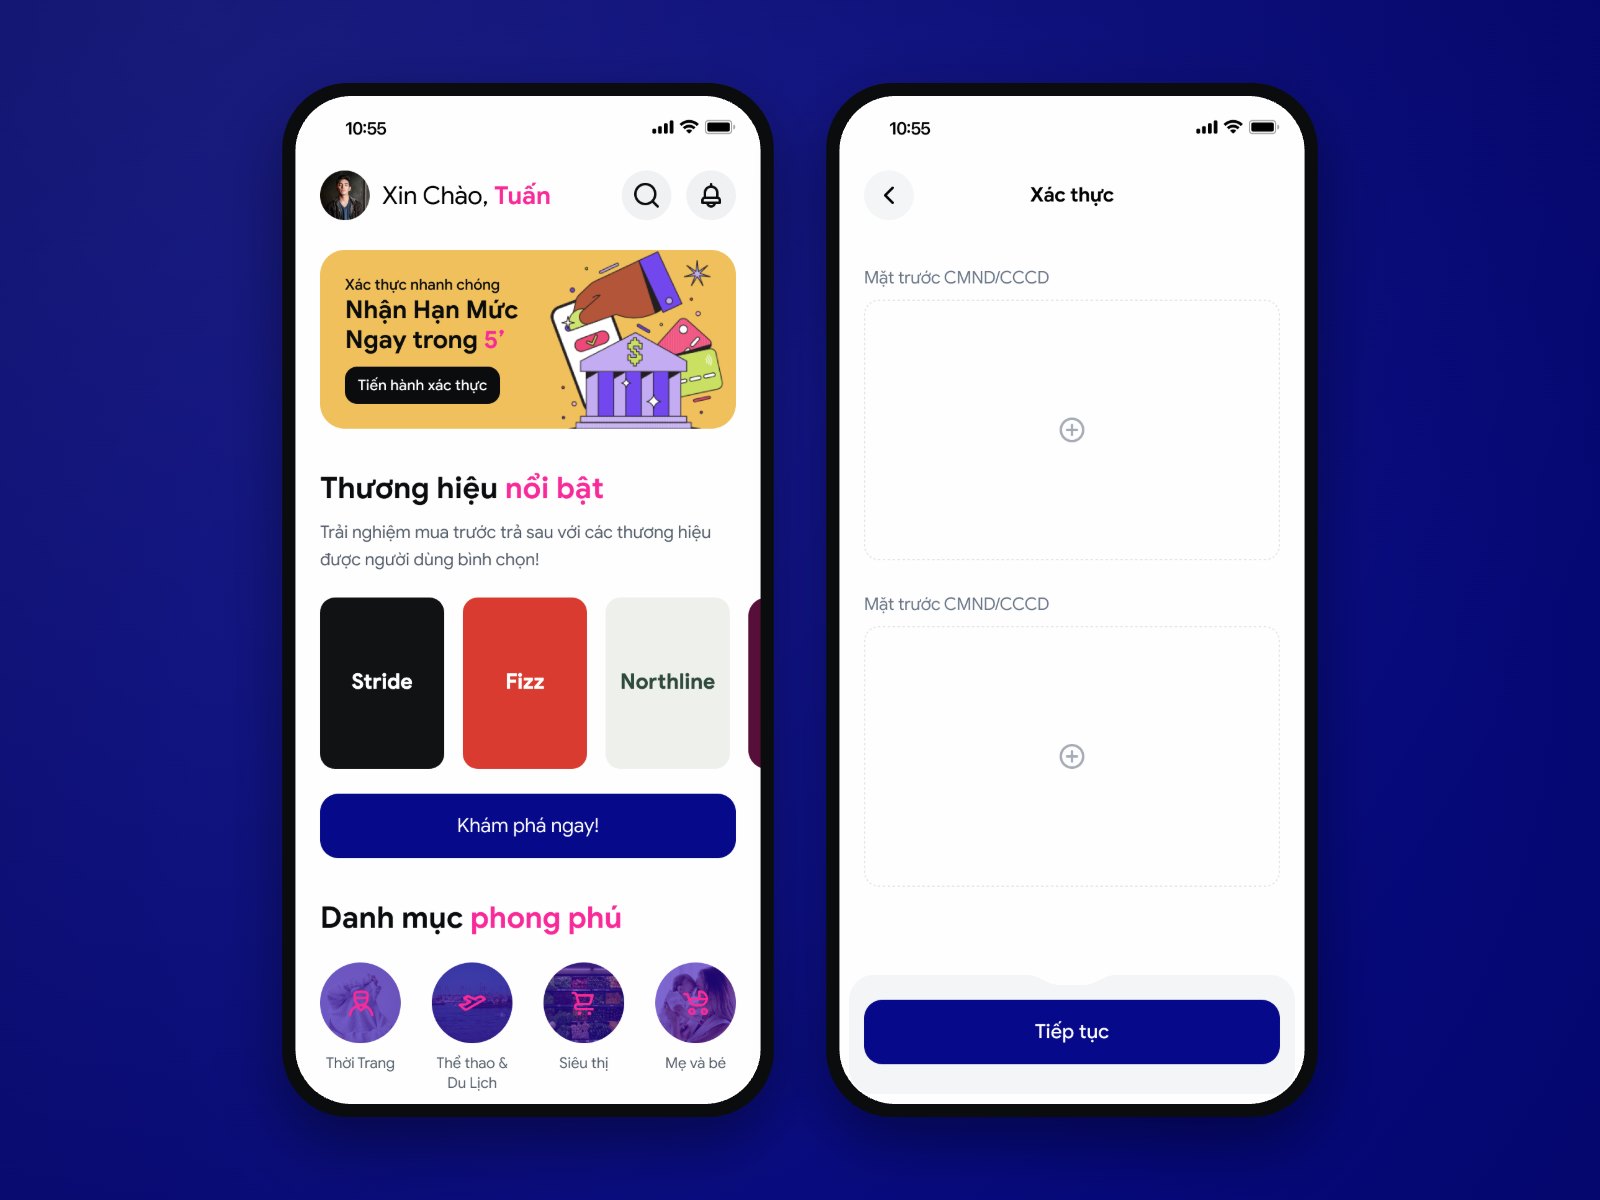
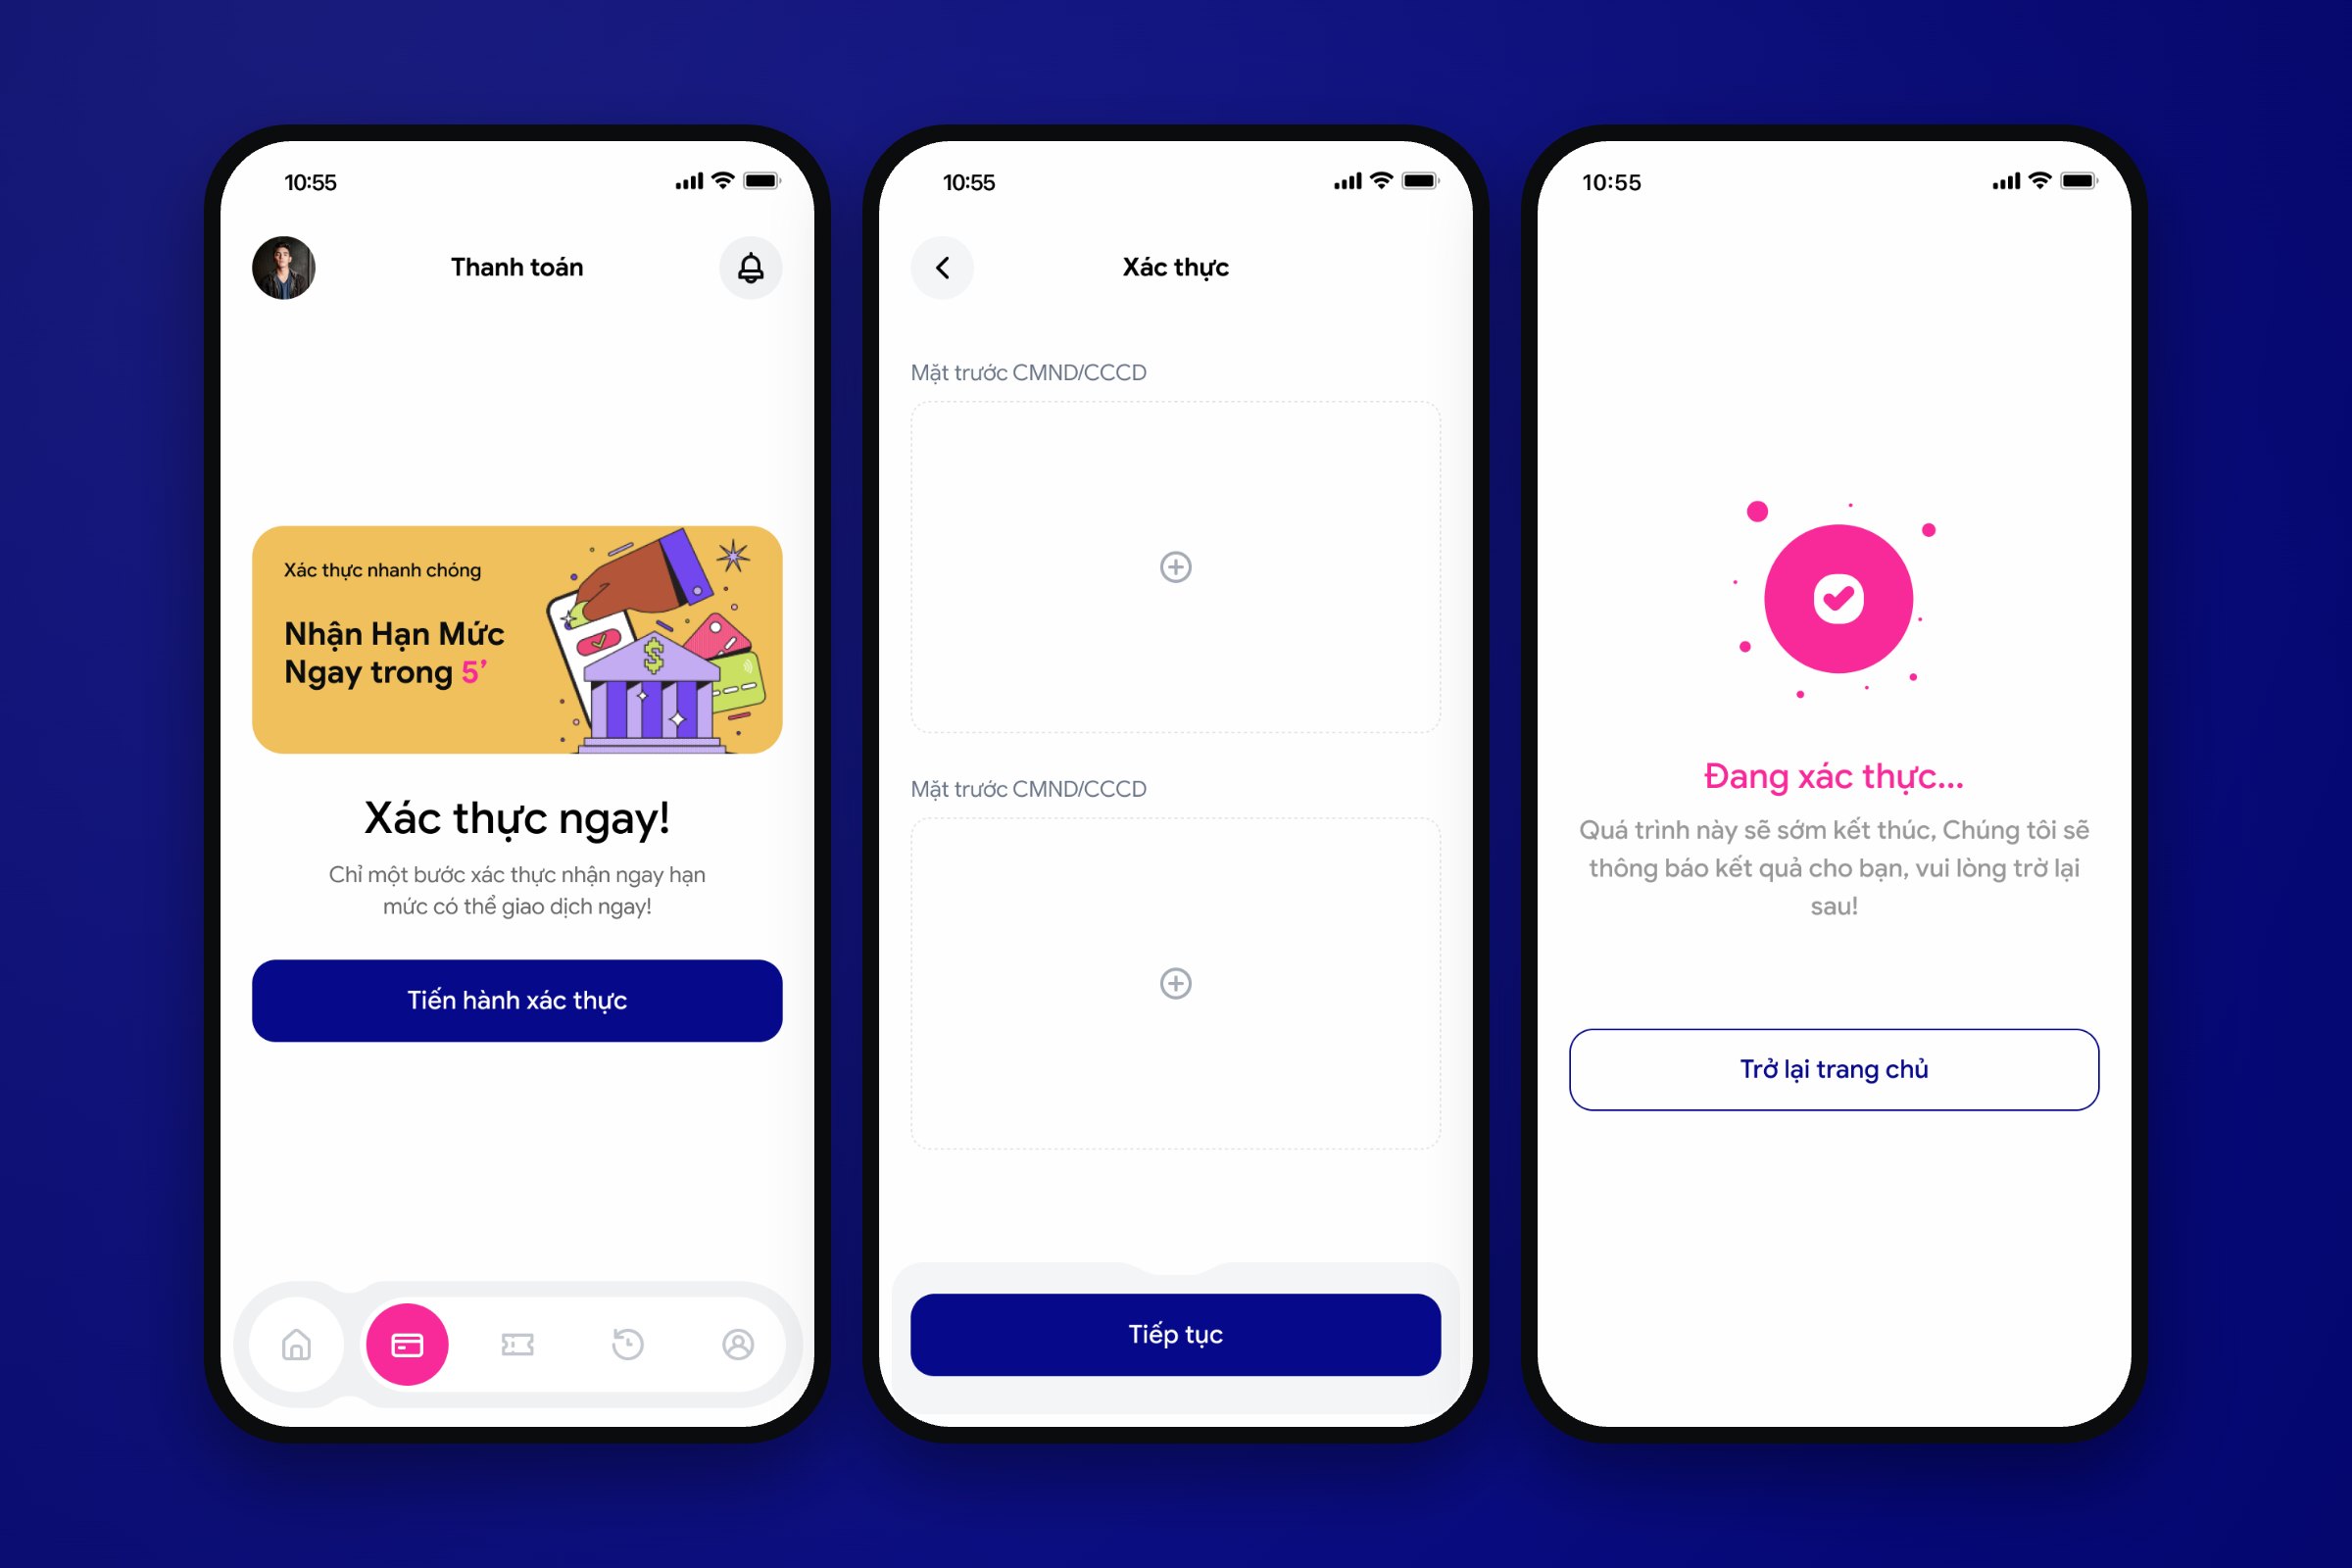
Slow approval was one of the three problems. The home screen opens with one invitation: verify once and get a credit limit. Verification takes three steps, personal details, an eKYC check and a short wait, and can start from the banner or the Payments tab. After that, every partner store works with the same limit.
From the research“I don't want to have to spend too much time applying for a loan.”

Decision
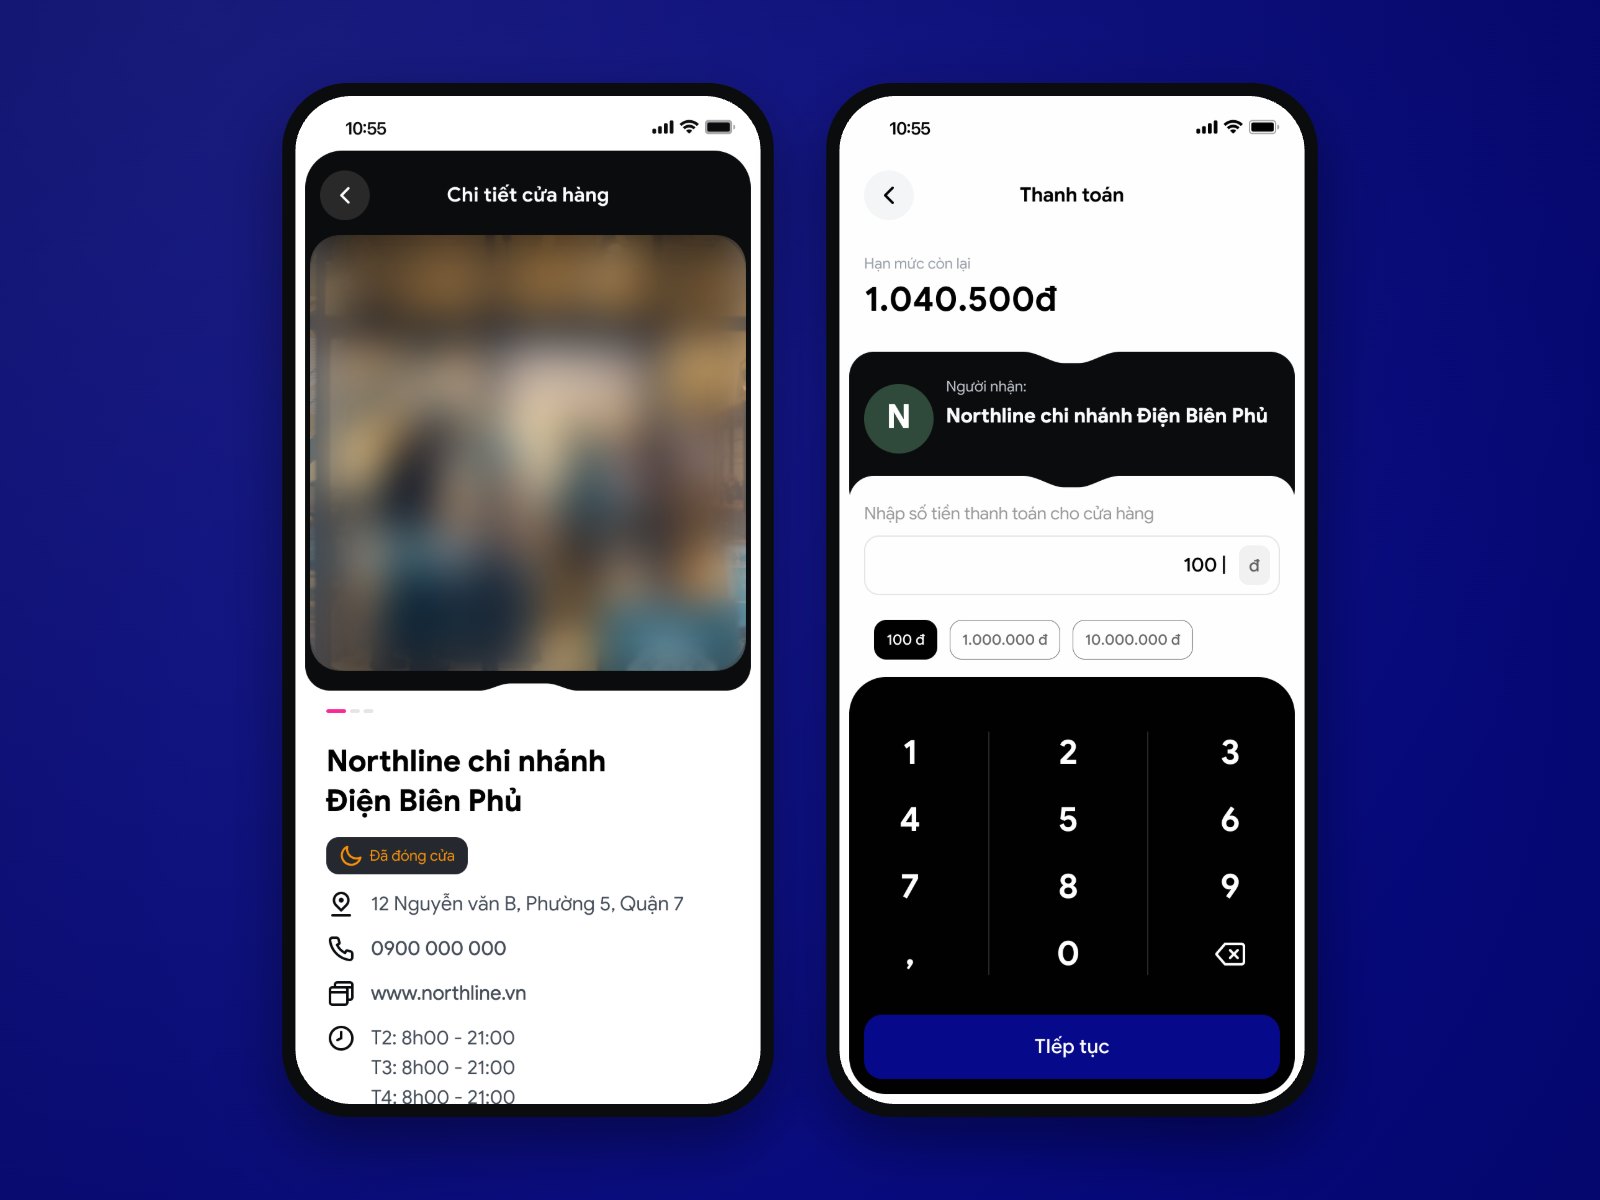
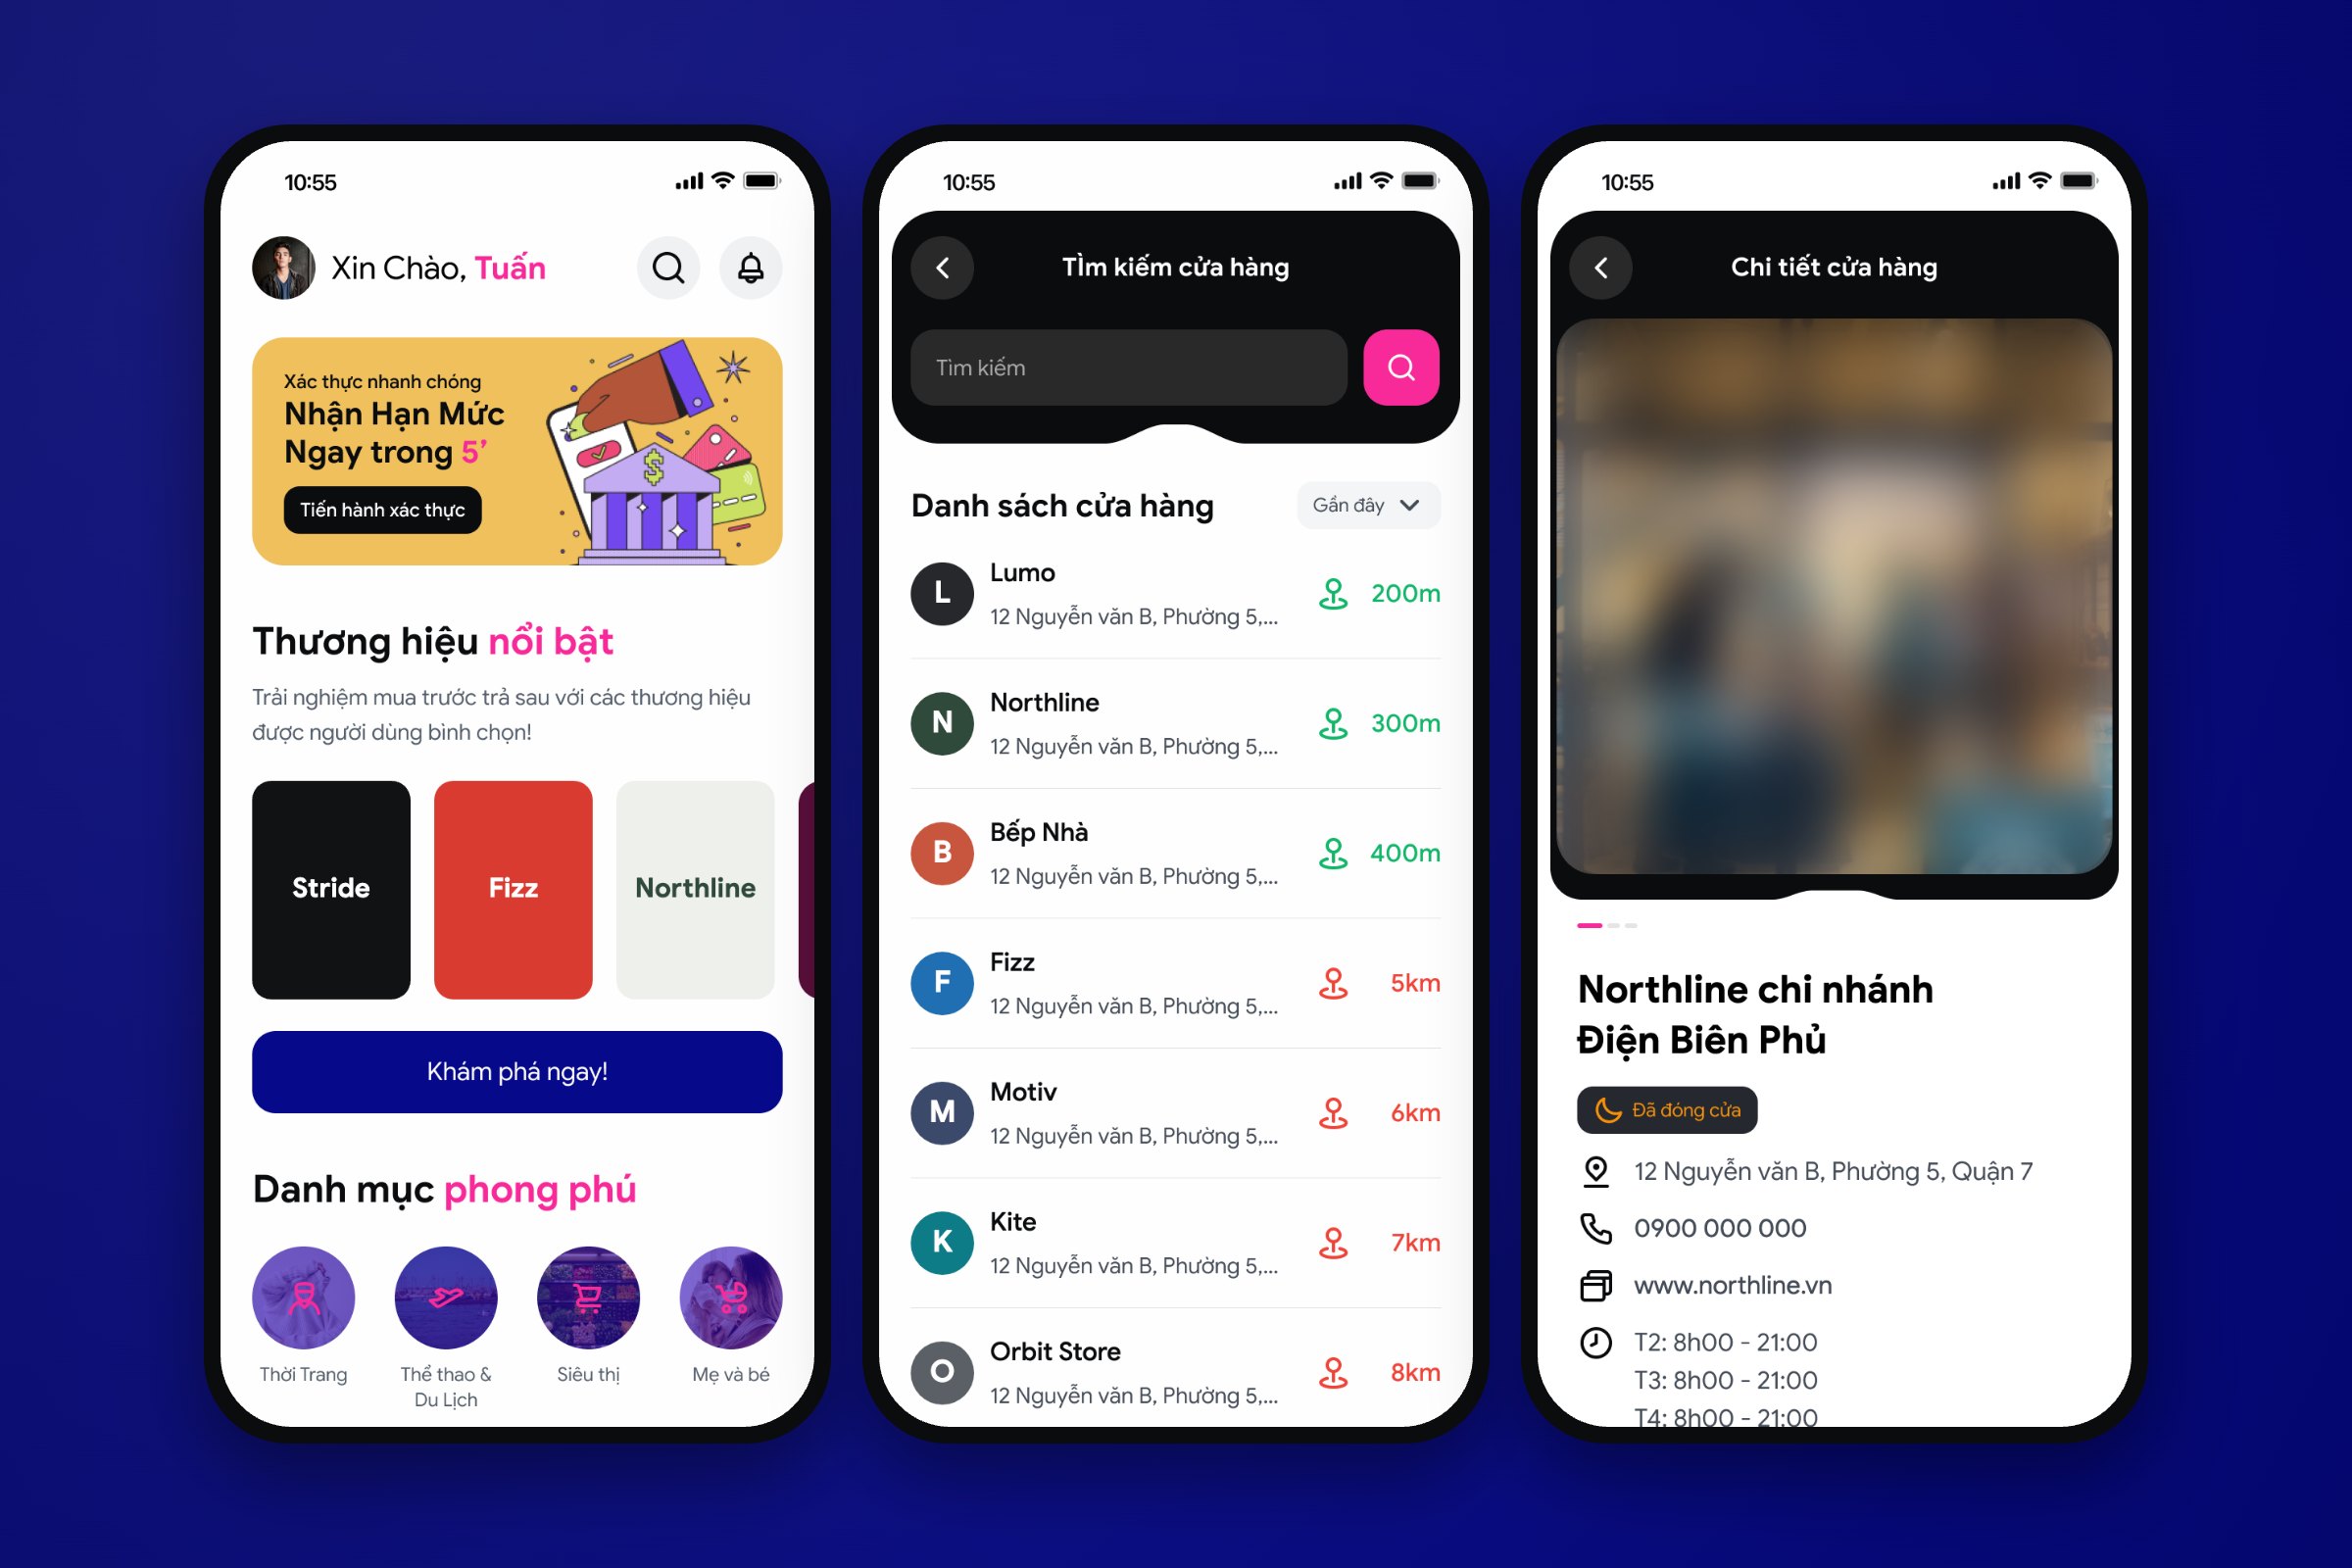
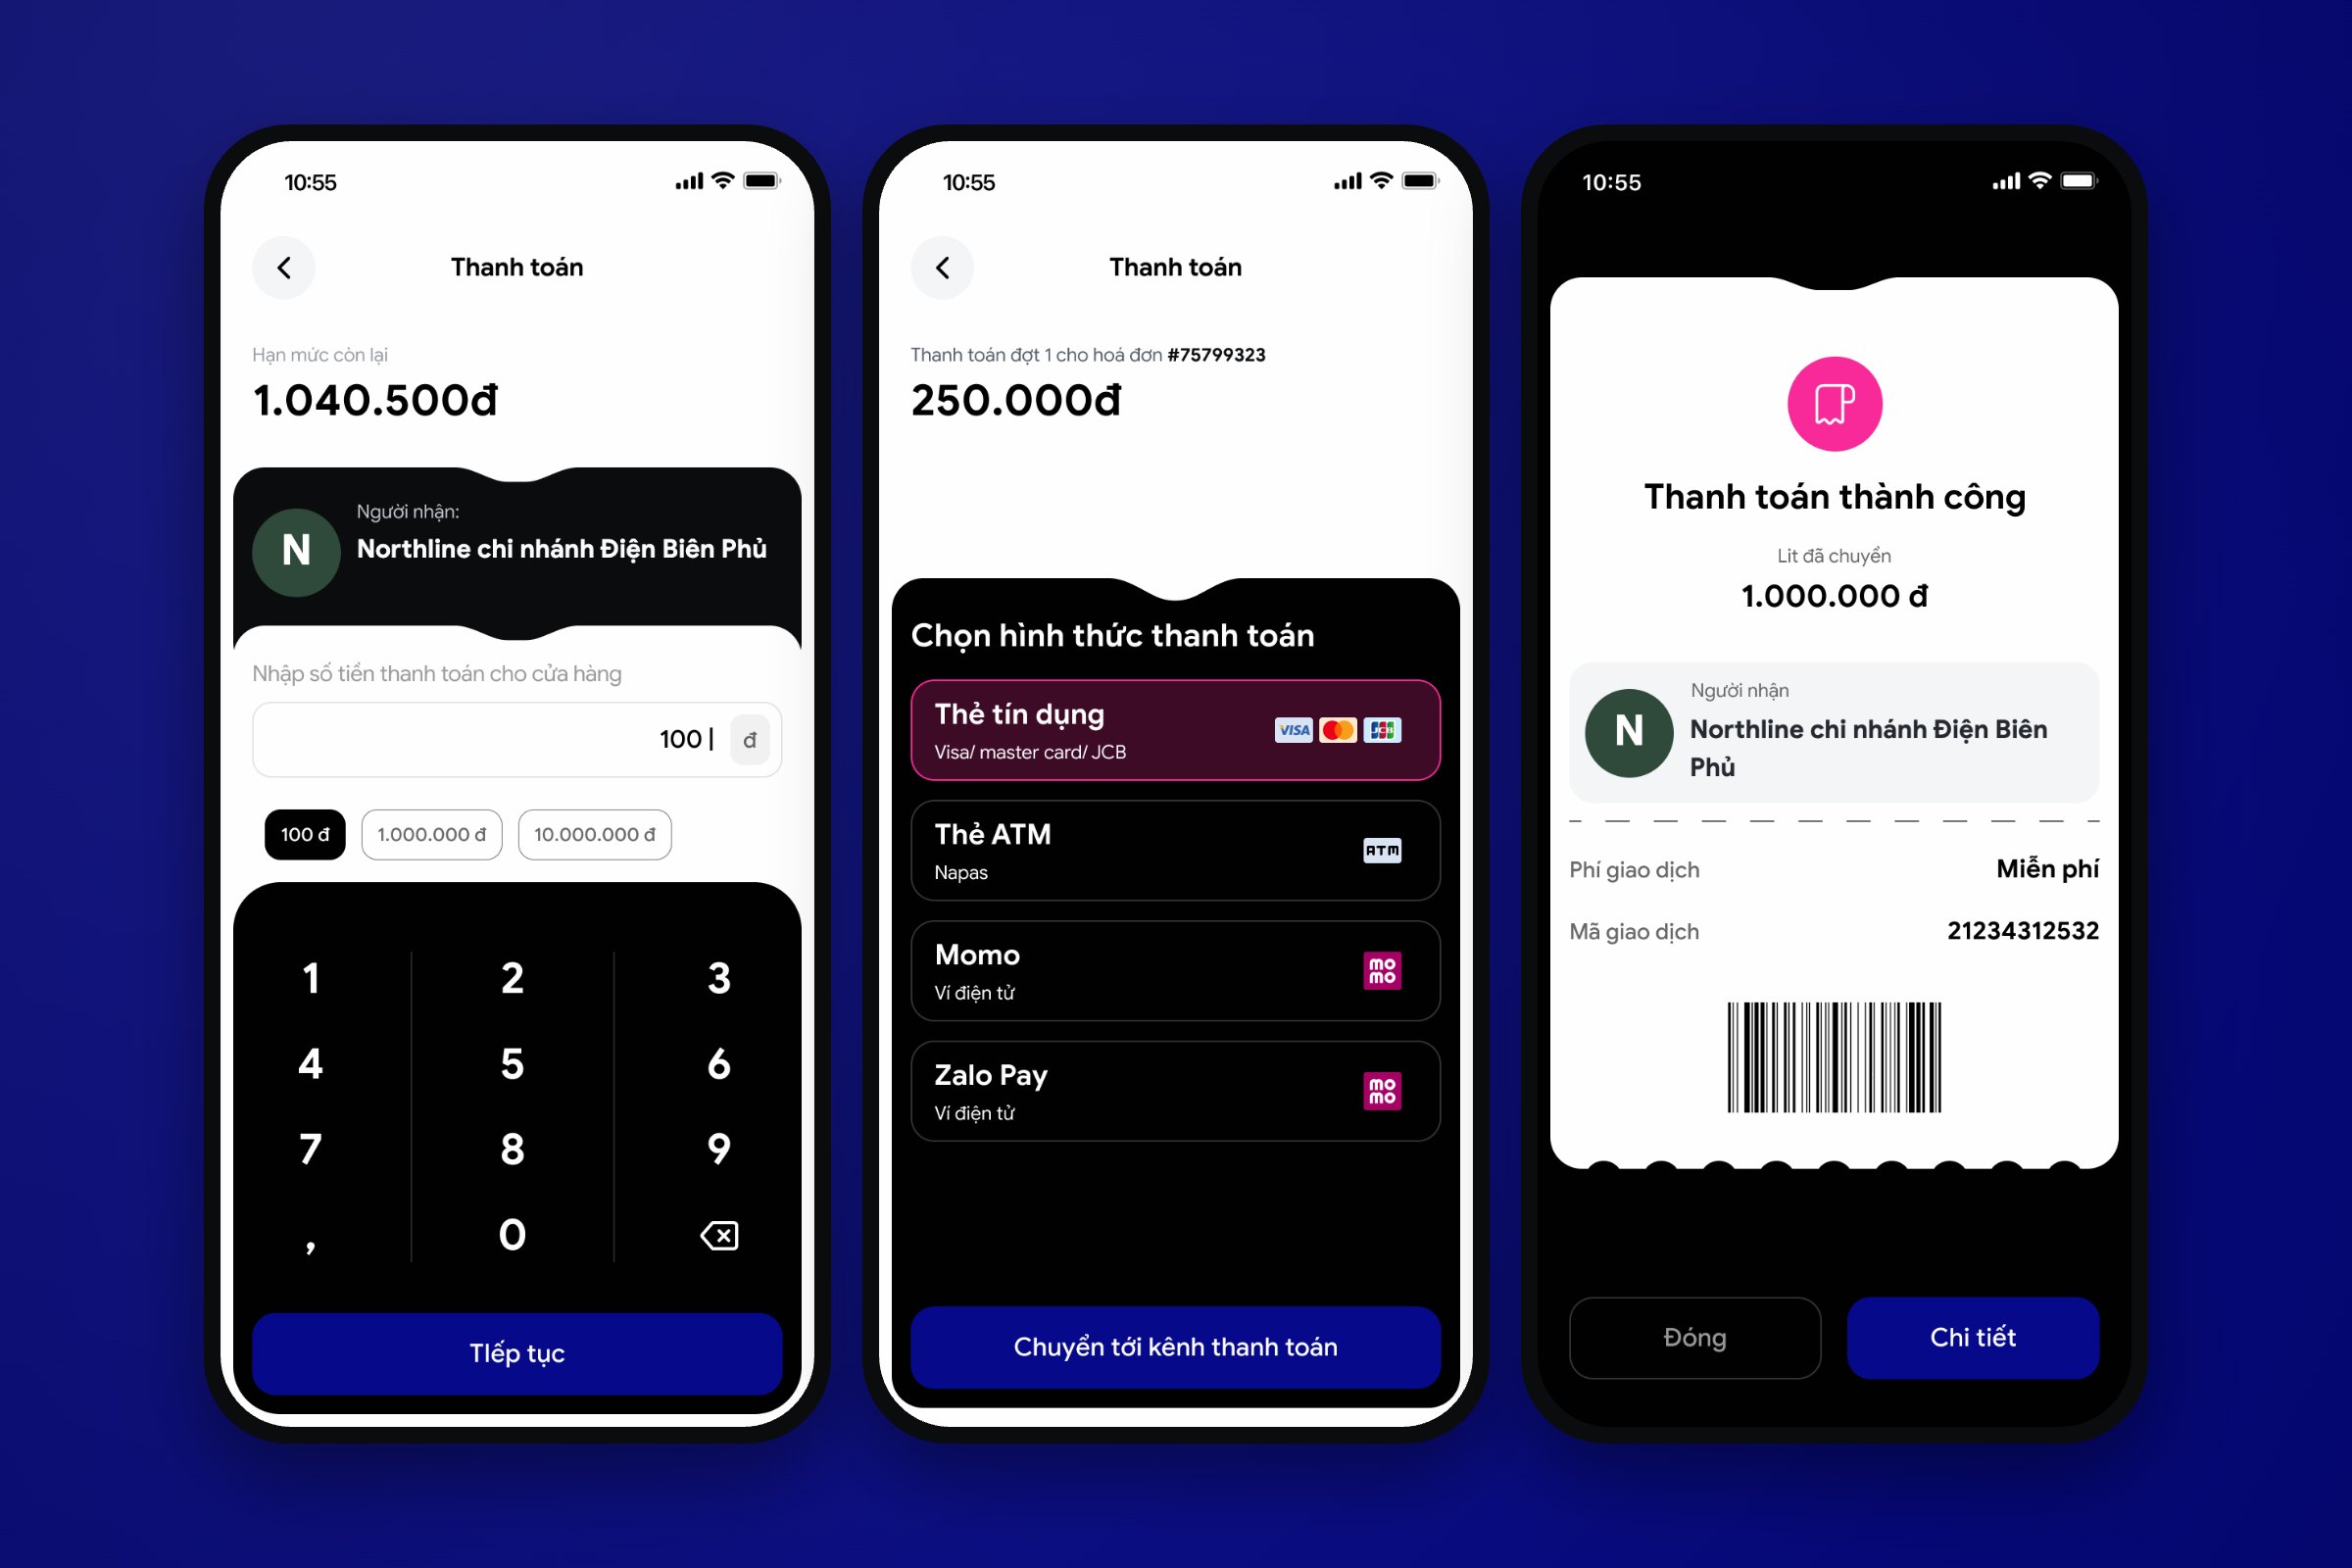
People did not want an account for every store. LIT lists partner stores by distance, with opening hours, a phone number and directions. At the counter, the user scans the store’s QR code, enters the amount and pays a quarter now. LIT settles with the store, and the receipt shows the three installments left.
From the research“Users want to be able to use a single payment platform to buy items from multiple different retailers.”

Decision
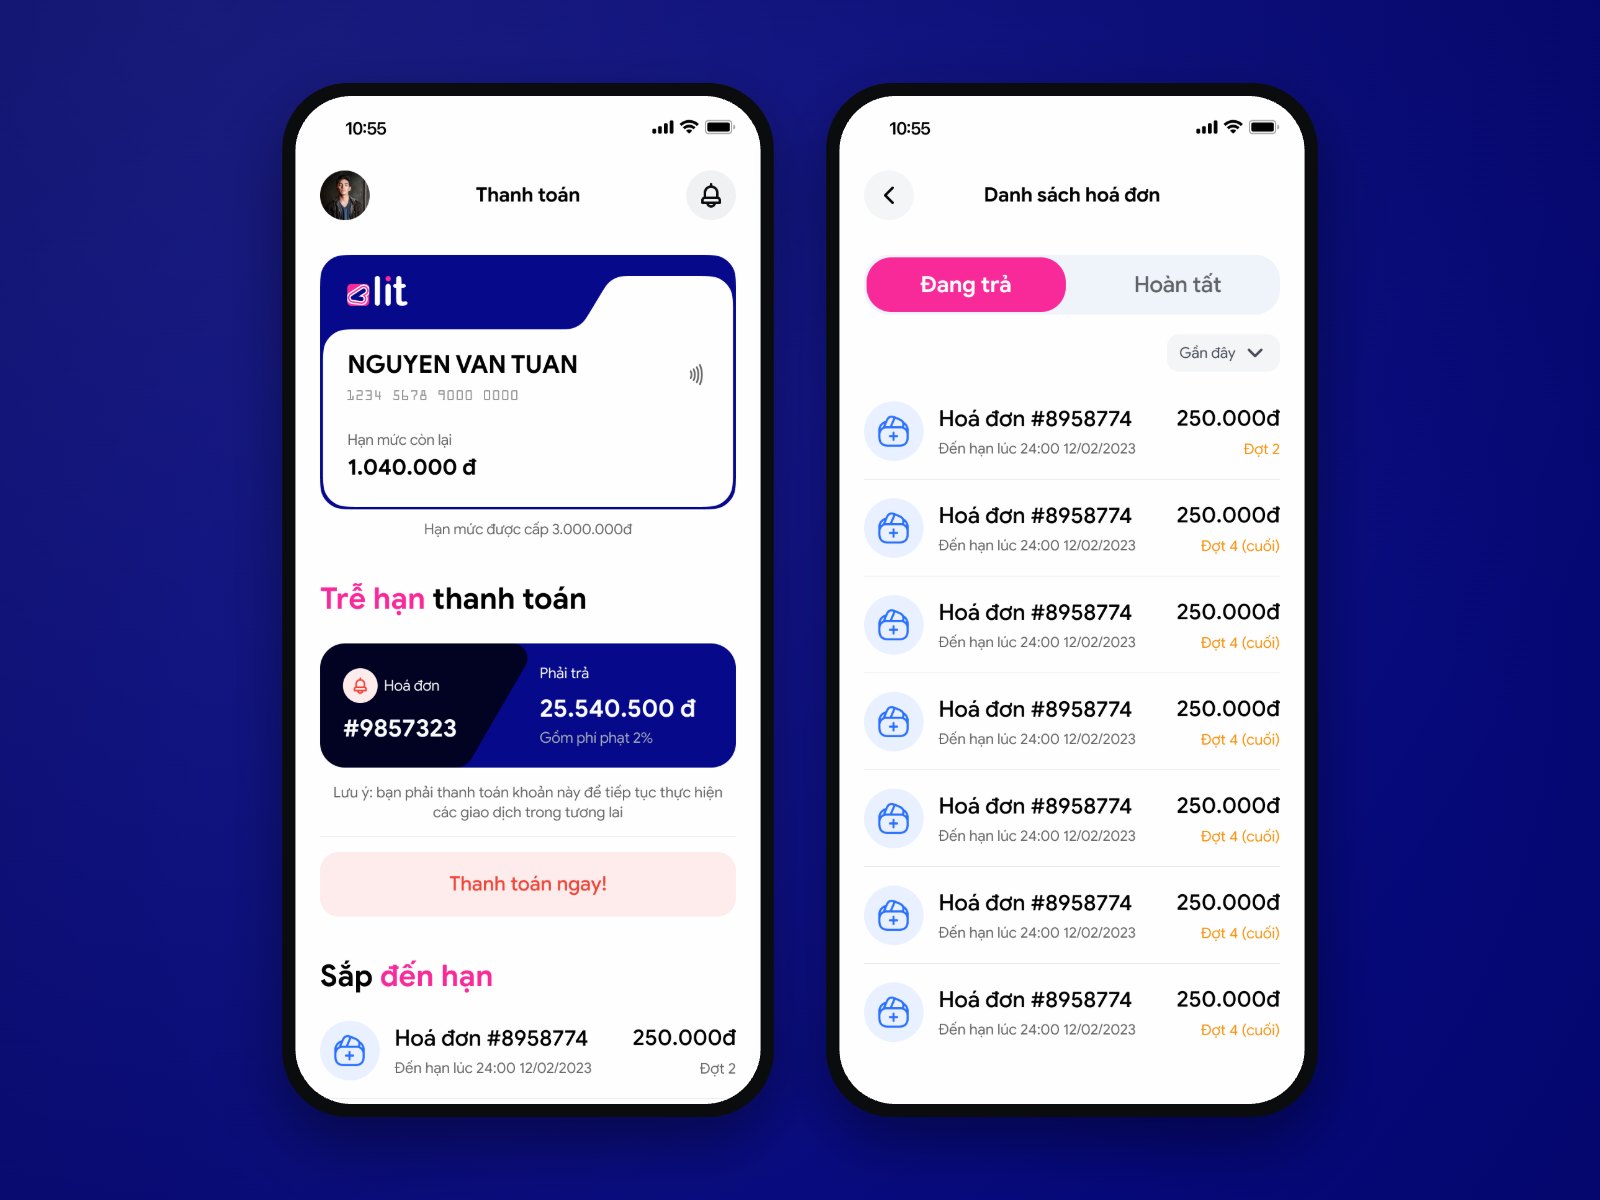
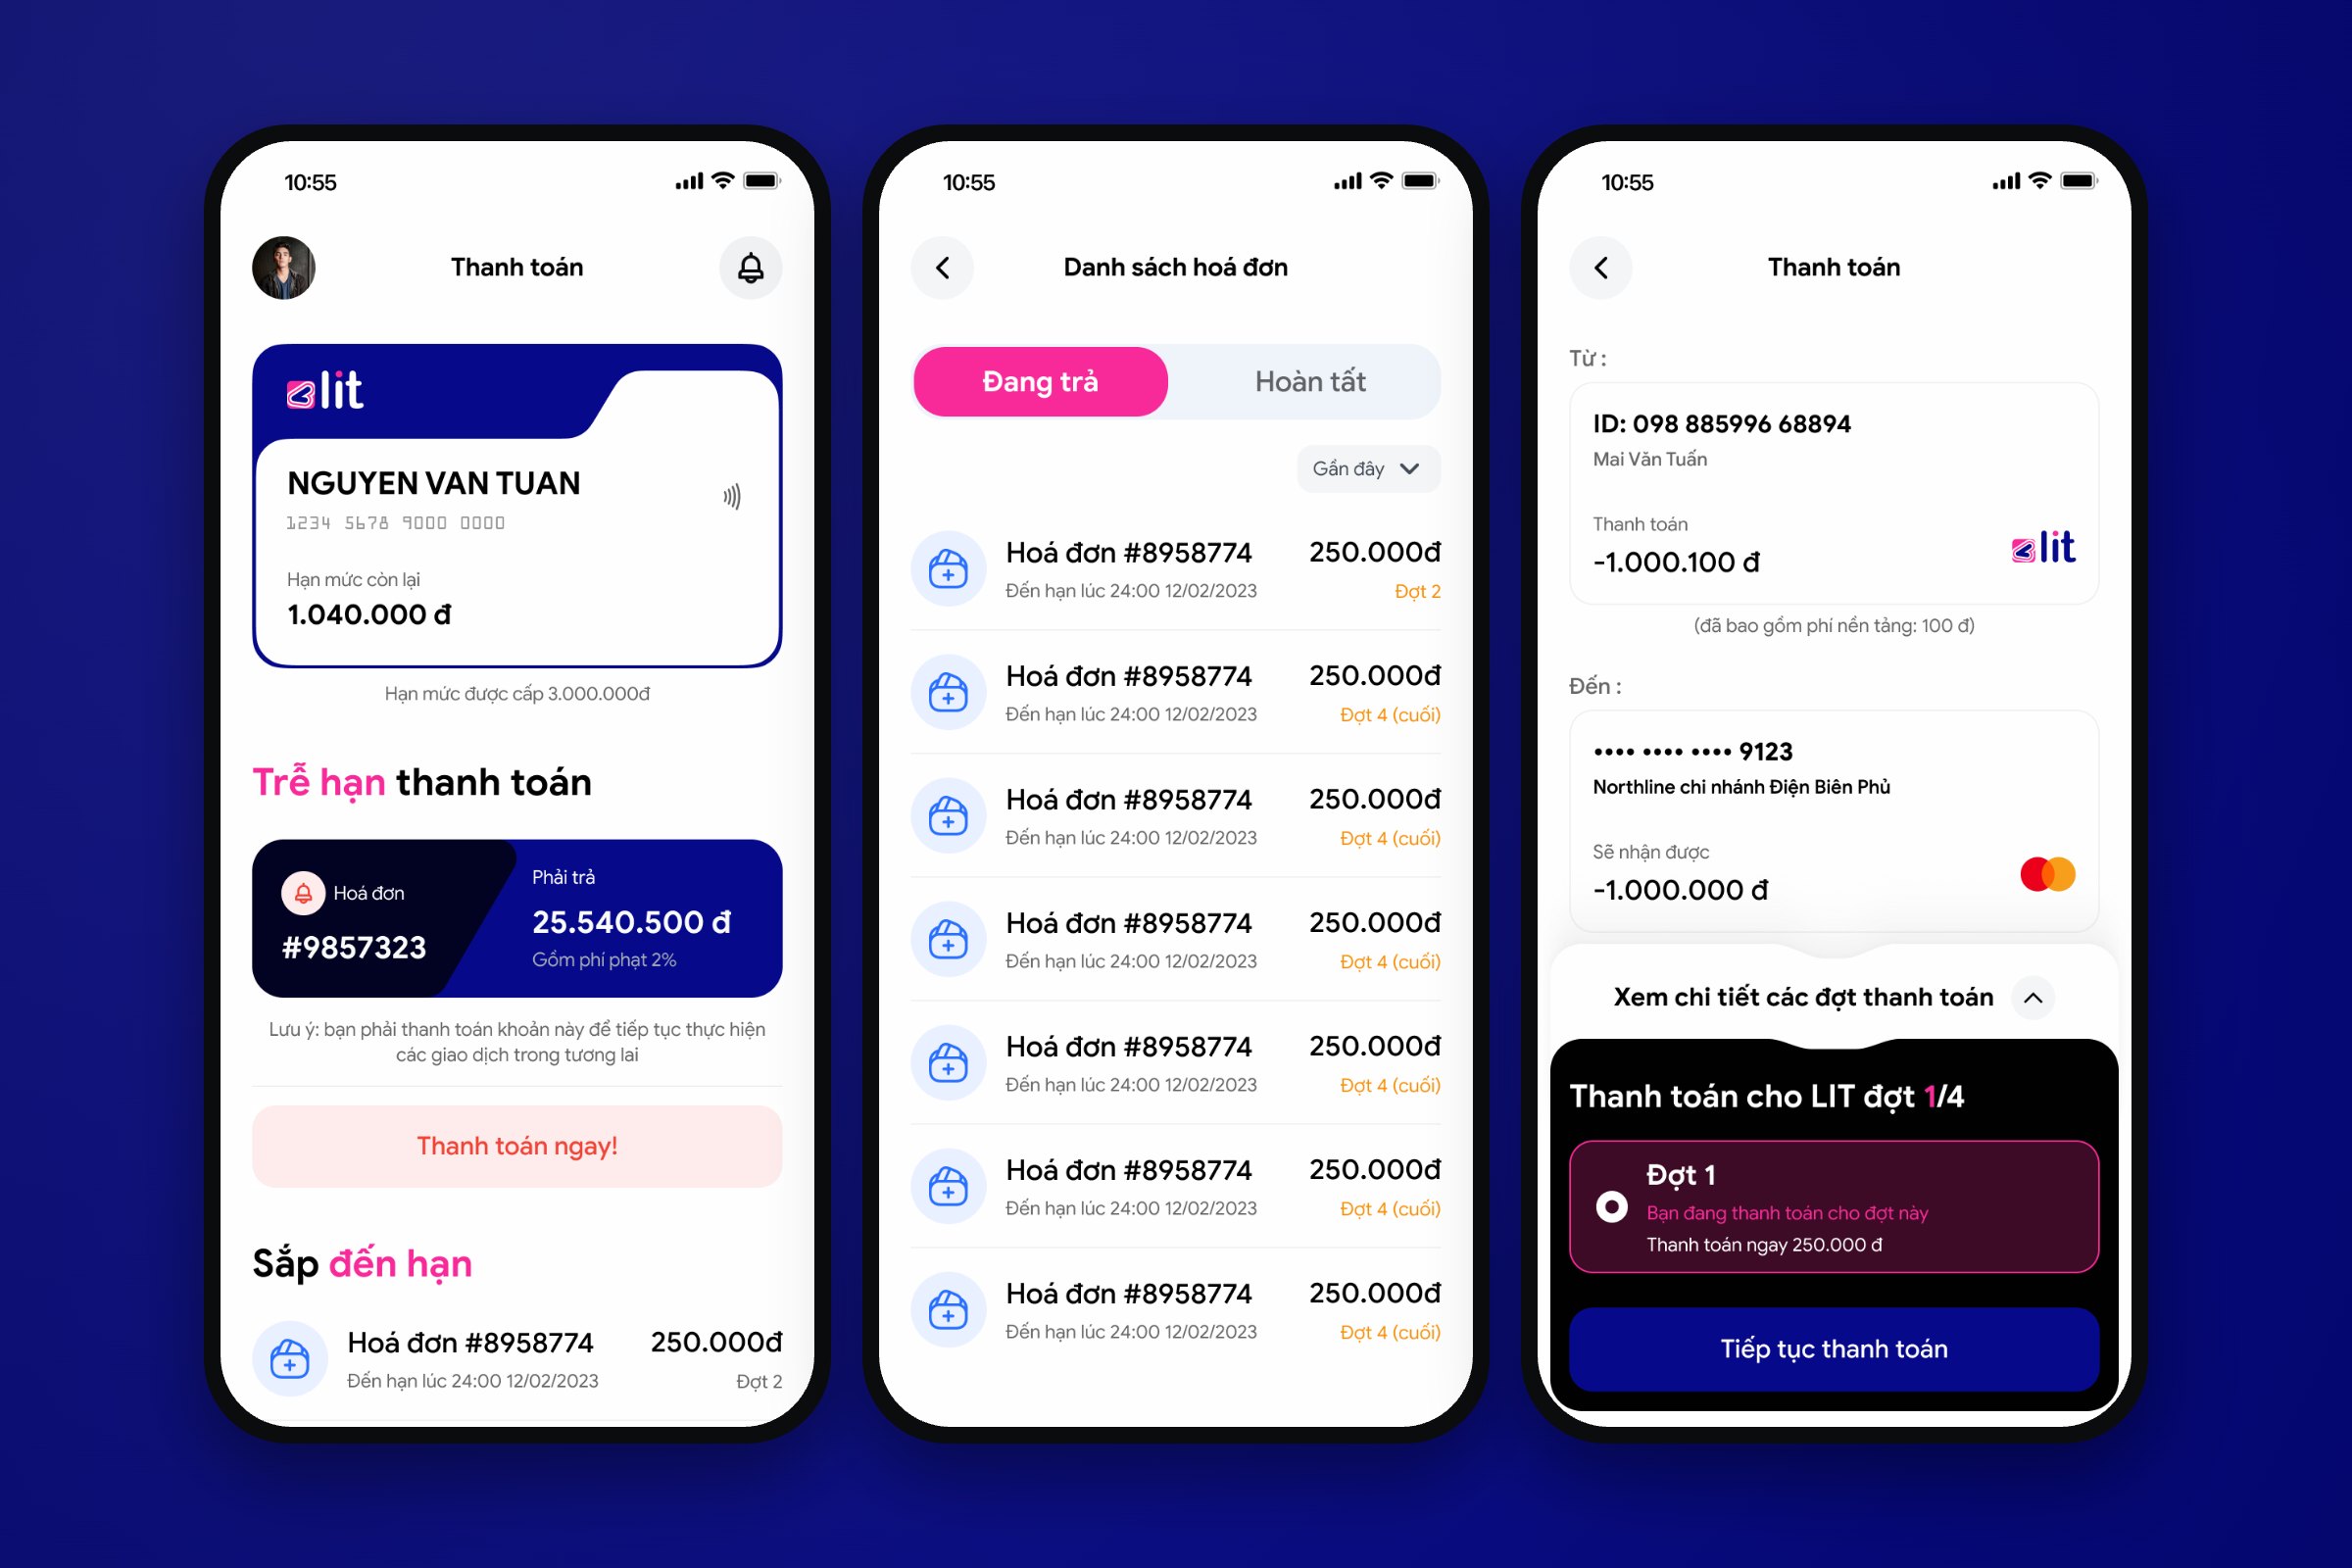
Falling into debt was one of the fears people named. The Payments tab opens with the remaining limit next to the limit granted. A late bill comes first, with its penalty fee and a note that new purchases wait until it is paid. Upcoming installments follow, each with its due date.
From the research“I am concerned that BNPL can lead to overspending.”

The app
The interface is in Vietnamese, for the market it was designed for. The style guide, type scale and components come from Asgard.

Home and search, with nearby stores first, and store details.

Identity verification for a credit limit.

Checkout at a partner store.

Payments: limit, late bills and upcoming installments.

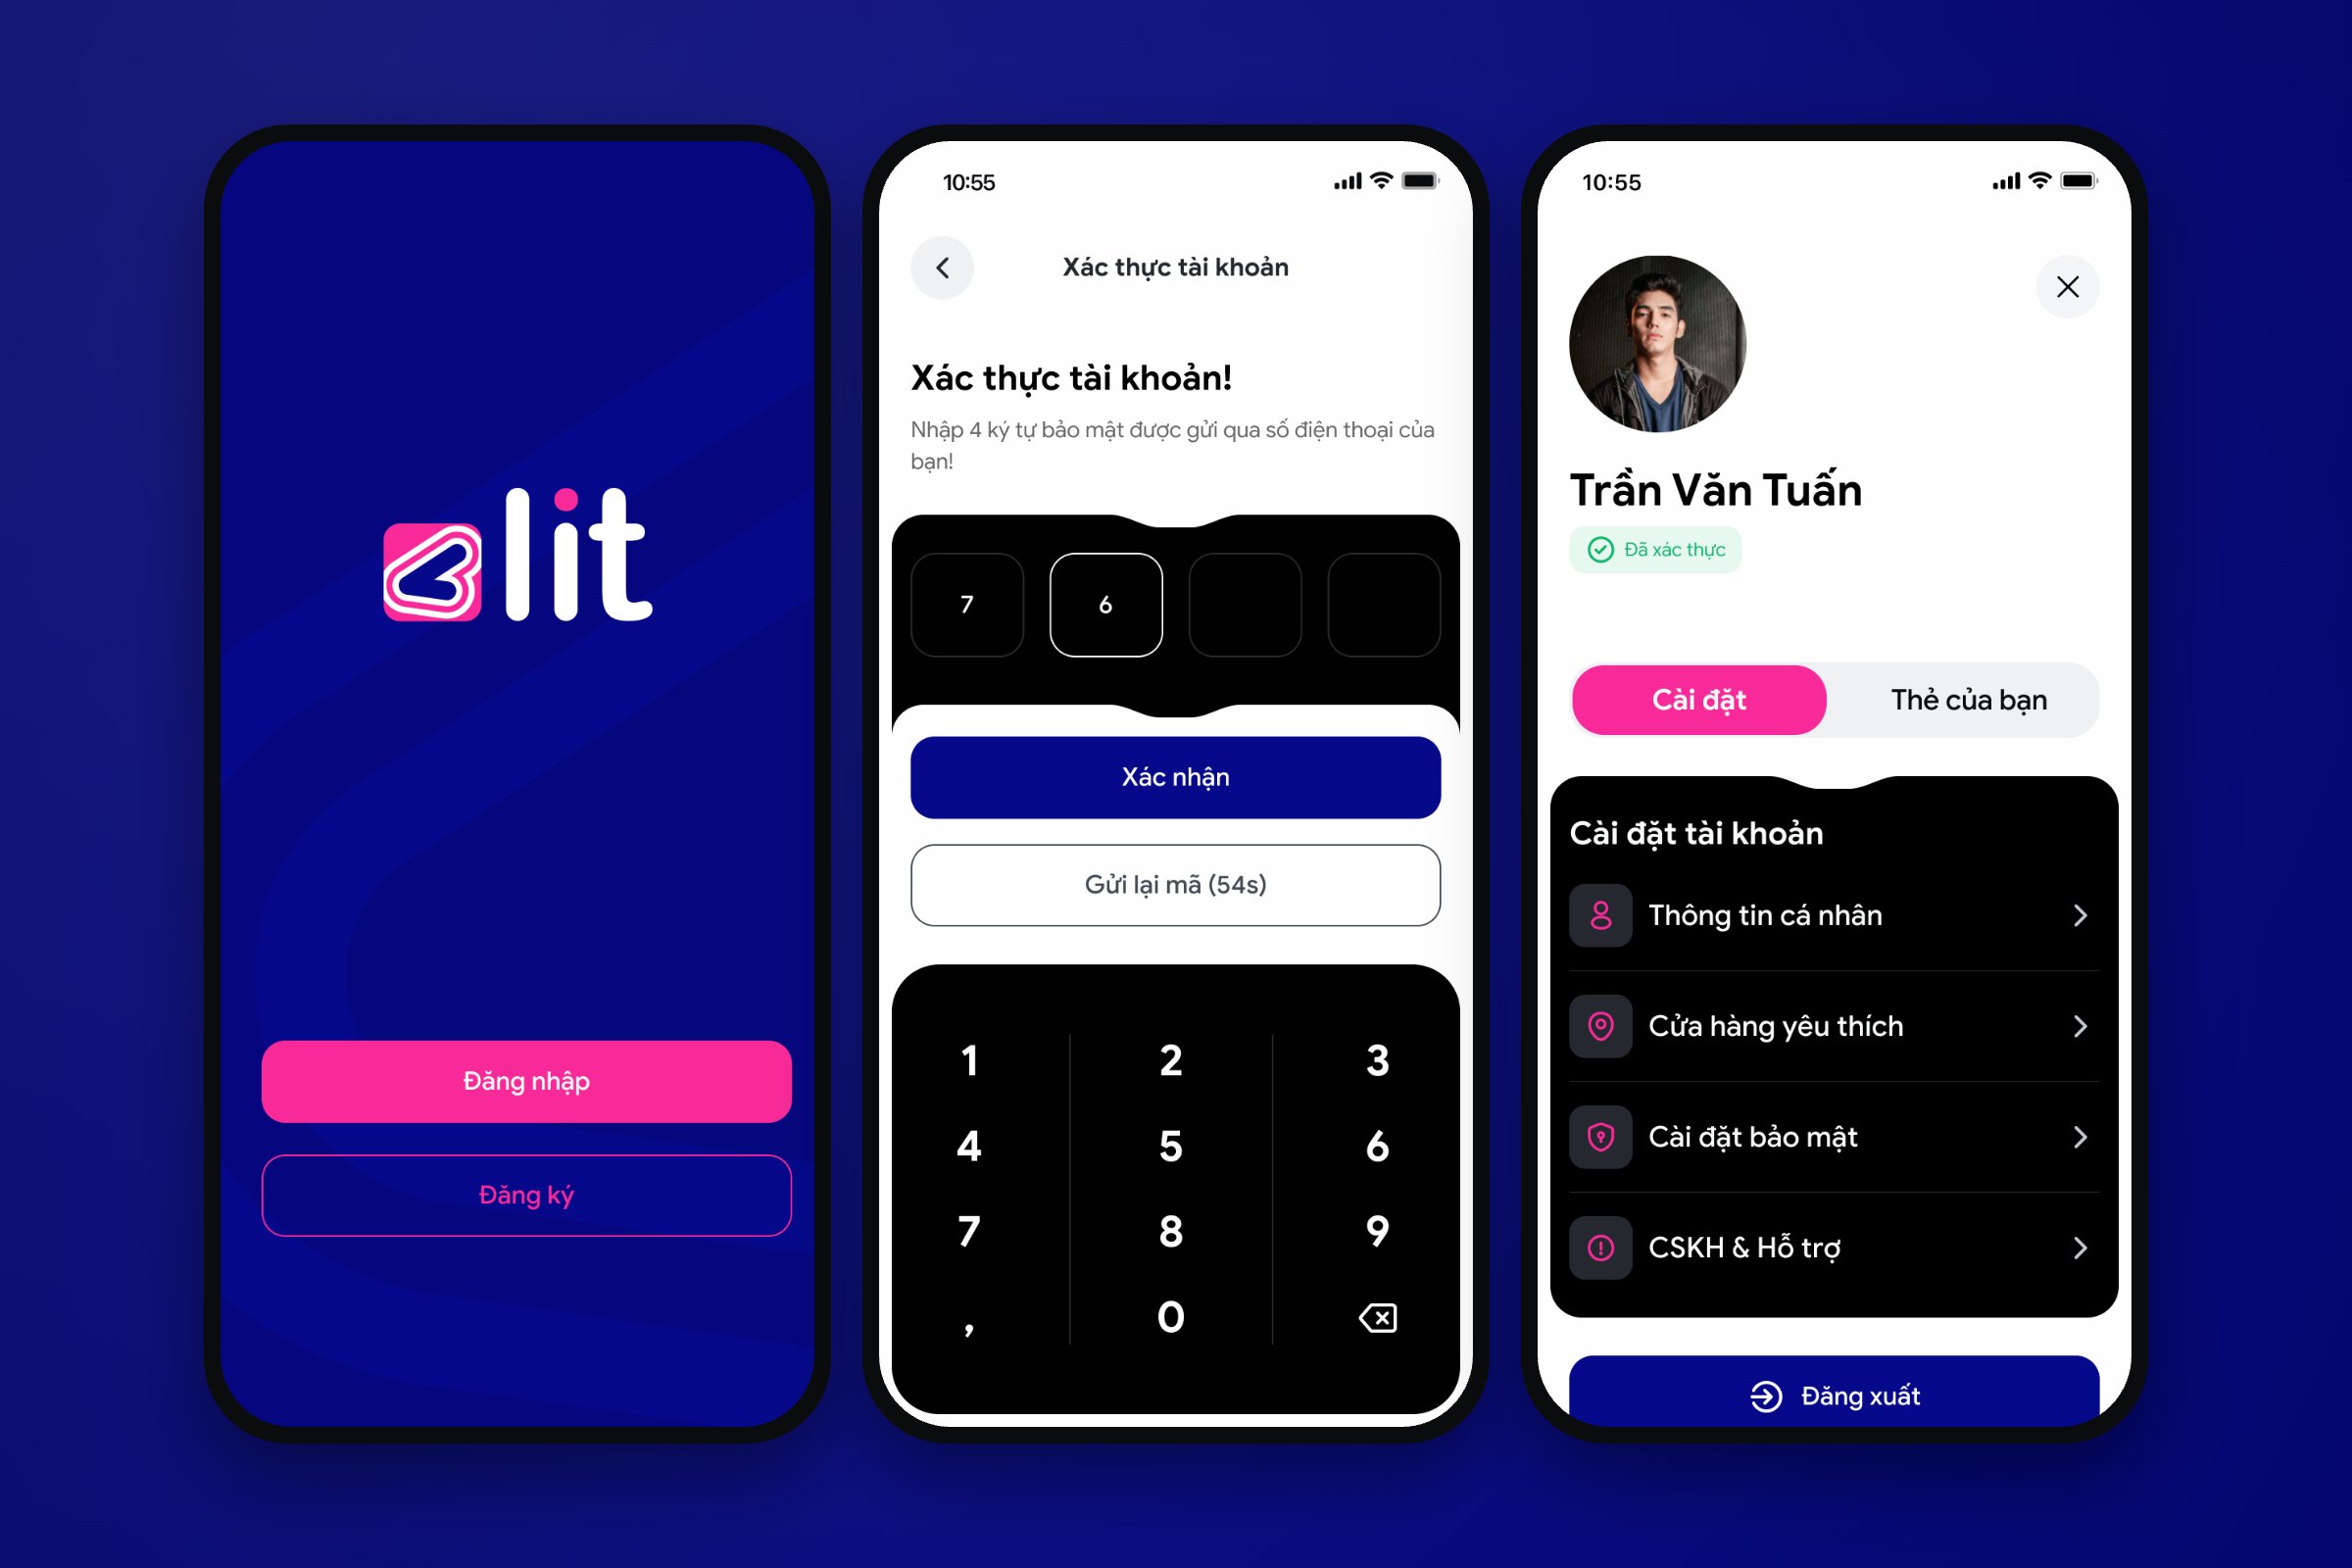
Sign-up with OTP by phone, and the profile with support.
Outcome
I handed LIT’s team the research, from problem statement to success metrics.
With it went a sitemap, a style guide and eight app flows, built on Asgard.
I proposed five metrics to track after launch: new sign-ups, usage frequency, average order value, customer lifetime value and referral score.
From problem statement to success metrics.
Built from the survey and interviews.
BNPL and credit services in Vietnam, 2023.
From registration to profile and support.
Counted in the project file. These figures describe the work, not its impact.
What I learned
LIT’s survey told me what people wanted: to pay later, in installments, without a slow approval. The competitor review showed where the real gap was. MoMo already offered 0% interest at more than 12,000 partners, but only as a wallet paid back after 30 days. That made installments, not paying later alone, the core of the design. Now I put a client’s research next to the market before I draw.
The first token-based design system used across HPI’s products, built while the design team grew from one to four.